If you carry the BMW Motorrad card from U.S. Bank, U.S. Bank has announced a simpler rewards structure. On October 13, 2026, U.S. Bank and BMW Financial Services North America announced redesigned BMW, MINI and BMW Motorrad Mastercard cards for new and existing cardholders in the U.S., with a flat earning structure and a bigger payoff when points go back into a BMW dealership or a BMW loan or lease.
The U.S. Bank announcement and BMW's matching press release describe the same program. Here's what it says, what it leaves out, and how to think about it as a rider.
Key points:
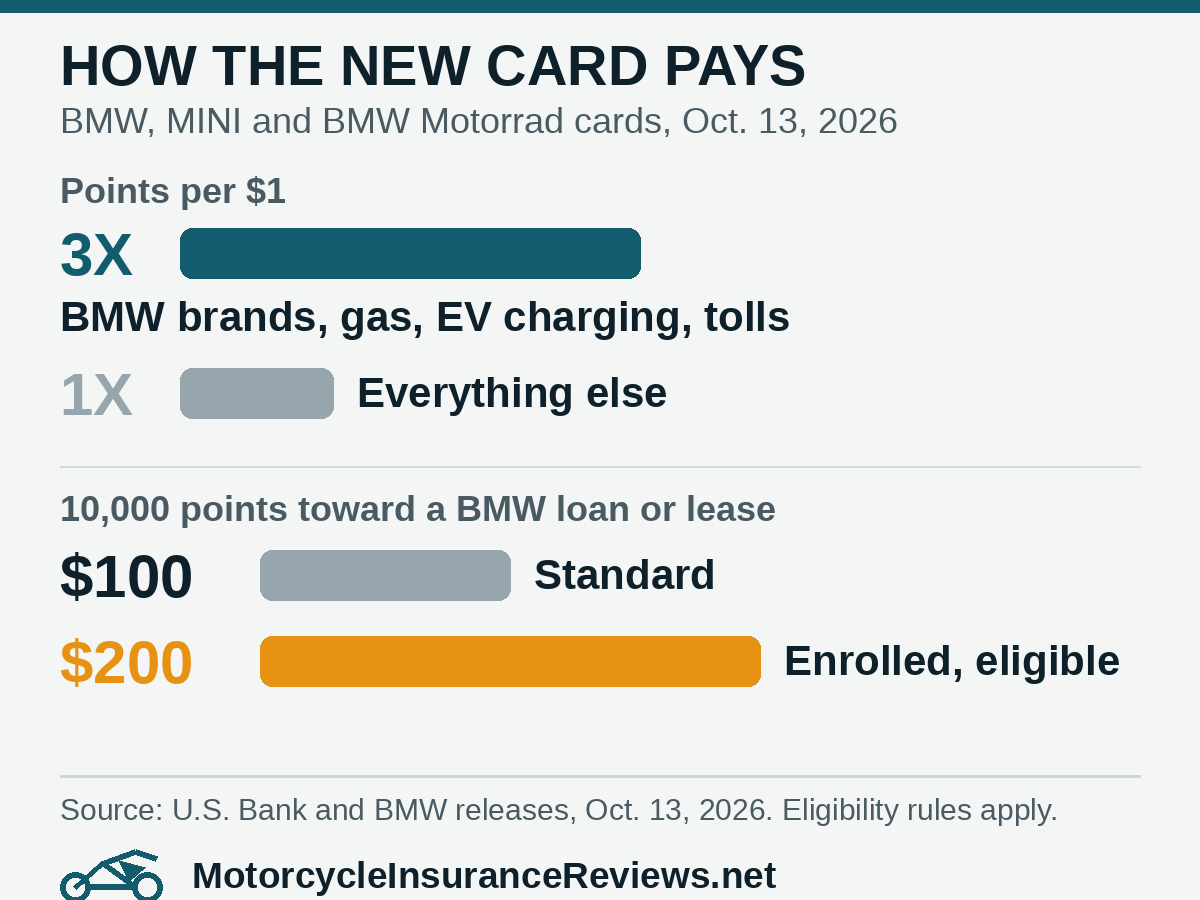
- 3 points per dollar at BMW, MINI and BMW Motorrad, and on eligible gas station, EV charging and toll purchases.
- 1 point per dollar on everything else.
- Points count double when redeemed at BMW, MINI and BMW Motorrad dealerships.
- 10,000 points = $200 toward an enrolled, eligible BMW Financial Services loan or lease, instead of $100.
- No annual fee, according to both releases.
What the card earns now
The earning side has two tiers, and both releases list them the same way.
- 3X points per $1: purchases at BMW, MINI and BMW Motorrad, plus eligible gas station purchases, EV charging and tollway charges.
- 1X point per $1: everything else. The releases call it "dollar-for-dollar" points.
For a rider, the useful part is that fuel and tolls sit in the top tier alongside the dealer. Under the announced structure, every tank you put in your bike, BMW or not, earns at the card's highest rate, as long as the station counts. The word to watch is eligible. Neither release defines which merchants count as a gas station or which toll systems qualify, and card issuers usually decide that by how a merchant codes its sales. A fuel stop inside a big-box store or a warehouse club may not code as a gas station.
What a point is worth
This is where the program rewards keeping your money inside BMW.
The releases give one worked example. Ten thousand points are worth $100 toward a BMW Financial Services loan or lease, or $200 if the loan or lease is enrolled and eligible. That works out to 1 cent per point at the standard rate and 2 cents per point with enrollment.
Points are also worth double when redeemed at BMW, MINI and BMW Motorrad dealerships. That covers the Motorrad side of the program: service, parts, gear and accessories bought from a BMW Motorrad dealer are the obvious places a rider would spend points. The releases don't say whether every dealer participates, or whether dealer redemptions have a minimum.
Put the two halves together and you get the card's best case. By our math from the releases' own example, 3 points per dollar redeemed at the example’s 2 cents each is about 6 cents back per dollar on eligible BMW, fuel and toll spending when applied to an enrolled, eligible loan or lease. The releases describe double value at dealerships but do not give a separate cents-per-point dealership example. Redeemed some other way, or earned on everyday 1X spending, the return is much lower.
The releases also mention Auto Sweeps, which apply points automatically toward loan or lease payments, and a BMW Card Extend Pay feature that lets eligible cardholders spread eligible BMW, MINI and BMW Motorrad purchases and services over time. The exact Extend Pay terms belong in the card's own disclosures, not in a press release, so check them there.
What's different from the old card
The previous versions of these cards launched in August 2020. BMW's 2020 announcement advertised "up to 5x rewards" at BMW, MINI and BMW Motorrad and accelerated rewards on gas and restaurants, with points usable at dealerships, toward vehicle payments, or for travel or cash back.
That makes a direct comparison tricky. The 2020 release didn't give point values, and we couldn't confirm what existing cardholders earned right before this change. The 2026 version is clearly flatter, with one 3X tier and a stated value for loan and lease redemptions. Whether it beats what you have depends on how you were using the old card.
What the announcement doesn't settle
Some details matter if you already hold the card.
- Timing for current cardholders. Both releases say the changes reward new and existing cardholders, but neither gives a date when existing accounts switch over, or says whether earning categories change on a specific statement.
- What "eligible" means. Eligible gas, EV charging and toll purchases, eligible loans and leases, and eligible Extend Pay cardholders all appear without definitions.
- What happens to old points. Neither release says whether points earned under the 2020 structure keep their value or redeem on the new terms.
- Introductory offers and rates. The announcement mentions a welcome offer and introductory financing, but those terms can change and the release isn't a cardholder agreement. We left the specific figures out. Read the current terms on the application page before you apply.
U.S. Bank links the program to mybmwcreditcard.com. When we checked, the page itself didn't display the card terms, so the application flow or your cardholder notice is the place to confirm them.
If you ride a BMW
This announcement is about a credit card, not about your bike, your loan or your insurance. Points don't change what your BMW Financial Services contract requires, and nothing in either release ties the card to motorcycle insurance. A few practical steps make sense either way.
- Watch for a cardholder notice. If you already have the card, U.S. Bank's own notice is what governs when the new earning and redemption rules apply to your account.
- Check whether your loan or lease can be enrolled. The $200-per-10,000-points value only applies to an enrolled, eligible BMW Financial Services account.
- Plan redemptions around the dealer. If you'd spend the points on service, tires or gear at a BMW Motorrad dealer anyway, that's where the releases say they're worth the most.
- Don't carry a balance chasing points. Interest on a revolving balance can quickly outweigh a few cents per dollar in rewards.
We're reporting the program as announced. MIR has no affiliate relationship with this card and isn't recommending it. A credit card is a personal financial decision, and the right card depends on how you spend and how you pay.
What we still don't know
- When existing accounts move to the new earning and redemption rules.
- How U.S. Bank defines eligible gas, EV charging, toll, loan, lease and Extend Pay transactions.
- Whether points earned under the 2020 terms keep their value.
- Which BMW Motorrad dealers accept point redemptions, and whether there's a minimum.
References
- U.S. Bank: Expanded Benefits, Simplified Rewards for BMW, MINI and BMW Motorrad Card Holders (Oct. 13, 2026) — Earning tiers, dealership and loan/lease redemption values, Auto Sweeps, Extend Pay, no annual fee.
- BMW Group PressClub USA: same Oct. 13, 2026 announcement (attachment) — Confirms earning tiers, redemption values and BMW Motorrad coverage.
- BMW Group PressClub USA: 2020 U.S. Bank BMW/MINI/BMW Motorrad card launch (Aug. 20, 2020) — 'Up to 5x' rewards and 2020 redemption options.